My Business Is Profitable, So Why Don’t I Have Any Cash?
Sep 16, 2026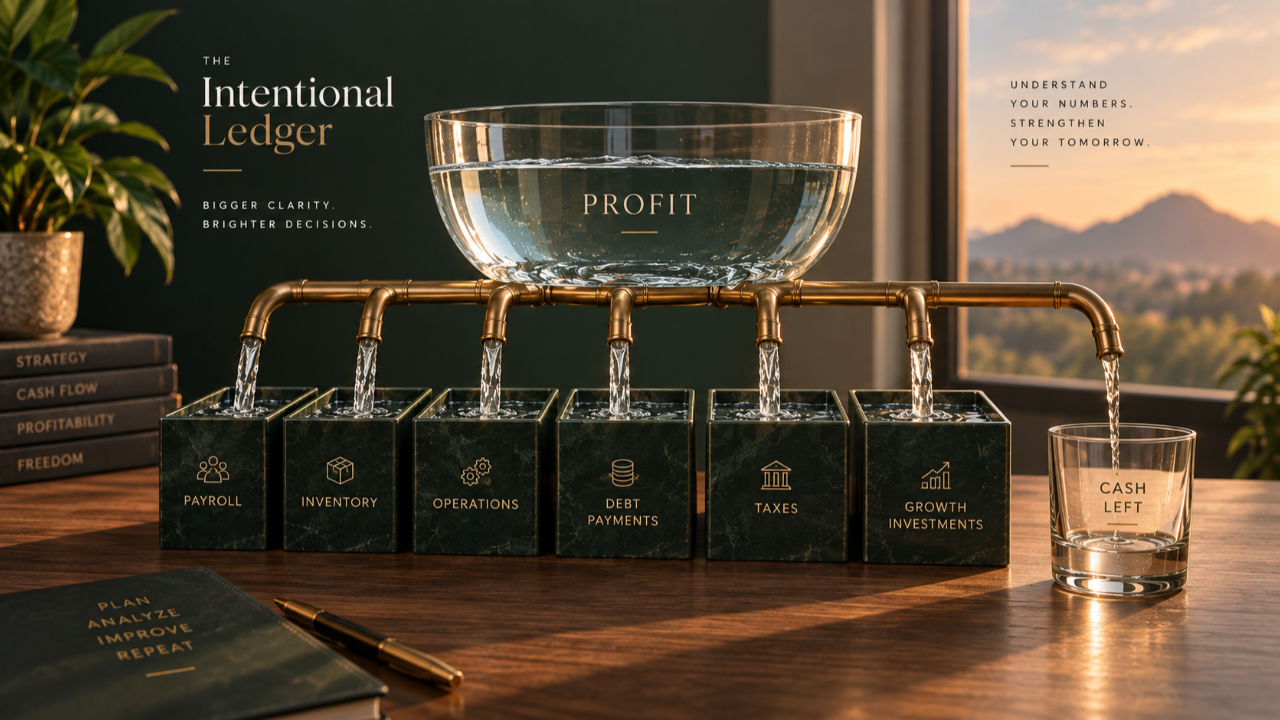
If your profit and loss statement says you made money, but your bank account is giving you a very different emotional experience, you are not imagining things.
This is one of the most common problems growing businesses face.
You can be profitable on paper and still feel cash-starved.
Why? Because profit and cash are related, but they are not the same thing.
A business can show a healthy profit while cash is tied up in receivables, inventory, debt payments, growth, taxes, or owner distributions. And if you are only looking at the P&L, you may be missing the part of the story that actually determines whether payroll, taxes, and next month’s bills get paid comfortably.
That is where financial strategy starts to matter.
Profit Is an Accounting Result. Cash Is a Timing Reality.
Your profit and loss statement answers an important question:
Did the business earn more than it spent over a period of time?
Your bank account answers another:
How much cash do we actually have available right now?
Those are not always the same answer.
For example, you may have recorded $100,000 in revenue this month, but if $40,000 of that is still sitting in accounts receivable, you do not actually have all of that cash yet.
Likewise, a loan payment may reduce your cash by thousands of dollars, while only the interest portion appears as an expense on your P&L.
This is how business owners end up staring at a profitable income statement and wondering who stole the money.
Usually, no one stole it.
It just went somewhere your P&L does not fully show.
1. Your Customers Haven’t Paid You Yet
Accounts receivable is one of the biggest reasons profitable businesses run short on cash.
You can make a sale today, recognize the revenue, and still wait 30, 60, or even 90 days to collect the money.
The business looks profitable.
The bank account looks less impressed.
If receivables keep growing, you may effectively be financing your customers while covering payroll, rent, vendors, and taxes yourself.
A few questions worth asking:
- How long does it actually take customers to pay?
- Which customers consistently pay late?
- Are payment terms too generous?
- Are invoices going out immediately?
- Are collections being followed up consistently?
Revenue is lovely. Collected revenue is considerably more useful.
2. Growth Is Eating Your Cash
Growth sounds like it should automatically improve cash flow.
Sometimes it does.
Sometimes growth walks into your office wearing expensive shoes and starts emptying the checking account.
Growing businesses often need to spend cash before the additional revenue arrives.
That can include:
- hiring staff
- buying inventory
- increasing marketing
- purchasing equipment
- moving into a larger space
- adding software or systems
- paying deposits
- increasing payroll before sales catch up
A business can become more profitable while simultaneously becoming more cash constrained.
This is why “we’re growing” and “we’re financially healthy” are not synonyms.
Growth needs to be funded intentionally.
3. Debt Payments Are Quietly Pulling Cash Out
Loan payments create another disconnect between profit and cash.
Your P&L generally reflects interest expense.
But your bank account feels the entire payment.
If you make a $5,000 loan payment and only $800 is interest, your P&L may show an $800 expense while your cash balance drops by the full $5,000.
Multiply that across vehicle loans, equipment financing, lines of credit, or acquisition debt, and suddenly the mystery starts clearing up.
This is one reason looking at only the income statement can be misleading.
Debt obligations matter because cash flow has to support them whether or not they appear as expenses.
4. You Are Carrying Too Much Inventory
Inventory is cash wearing a costume.
It sits on shelves instead of in your bank account.
If inventory levels rise faster than sales, the business may remain profitable while cash gets increasingly trapped in unsold product.
The same issue can show up in construction materials, restaurant inventory, retail goods, manufacturing inputs, or any business that has to purchase something before selling it.
The key question becomes:
How quickly does invested cash turn back into collected cash?
If that cycle is too slow, growth can become surprisingly expensive.
5. Taxes and Owner Distributions Are Not Always Reflected the Way You Expect
Owners often look at net profit and mentally treat it as available cash.
Dangerous little assumption.
Profit does not automatically mean that entire amount is safe to distribute.
The business may still need cash for:
- income taxes
- sales tax
- payroll tax
- future payroll
- debt service
- upcoming equipment purchases
- seasonal slowdowns
- working capital
Owner draws or distributions can also reduce cash without appearing as an operating expense.
So yes, the company may have produced profit.
No, that does not necessarily mean all of it is available to take home.
A better question is:
How much cash can the owner safely take without weakening the business?
That answer requires more than a P&L.
6. Your Business Has a Timing Problem
Sometimes the issue is not profitability at all.
It is timing.
Imagine this:
Payroll hits Friday.
Rent hits Monday.
A large customer pays Wednesday.
Technically, the business has enough money across the month.
Practically, Tuesday is unpleasant.
This is why cash forecasting matters.
A cash flow forecast shows when money is expected to come in and when money needs to go out.
It helps you see shortages before they become emergencies.
That changes the conversation from:
“Why are we short again?”
to:
“We are projected to be tight six weeks from now. What do we want to do about it?”
That is a much better place to operate from.
What Should You Look At Besides Profit?
If cash always feels tighter than expected, start looking at the business through more than one financial lens.
A good monthly review should include:
- profit and loss
- balance sheet
- accounts receivable
- accounts payable
- debt obligations
- cash balance
- upcoming tax payments
- owner distributions
- cash flow forecast
This is also where financial ratios and trends can help.
You do not need fifty dashboards glowing like the cockpit of a spaceship.
You need a few useful numbers that actually help you make decisions.
The Real Question Is Not “Did We Make Money?”
That is only the beginning.
The more useful questions are:
Where did the cash go?
What is coming next?
How much cash does the business need to operate safely?
What can we afford to spend, hire, invest, or distribute?
What happens if revenue drops 10%?
What happens if we grow 25%?
Those are CFO-level questions.
And they matter because businesses rarely get into trouble simply because no financial reports existed.
They get into trouble because no one translated the reports into decisions.
Better Numbers Should Lead to Better Decisions
Your financial statements should do more than tell you what happened last month.
They should help you decide what to do next.
If your business is profitable but cash still feels unpredictable, the answer is not necessarily to work harder, sell more, or panic quietly while refreshing the bank account.
Start by understanding where the cash is actually going.
That is often where clarity begins.
The Intentional Ledger is about making financial information useful—not just accurate.
Because good numbers are nice.
Better decisions are the point.
Need help understanding where your cash is going? CFO advisory can help turn your financials into a plan.
Ready to understand what your numbers are actually telling you?
Your financials should help you make decisions, not leave you with more questions. CFO advisory turns the numbers into clarity, strategy, and a plan for what comes next.
Stay connected with news and updates!
Join our mailing list to receive the latest news and updates from our team.
Don't worry, your information will not be shared.
We hate SPAM. We will never sell your information, for any reason.